
Restaurant Valuation Multiples: How to Value a Restaurant in 2026

Restaurant owners often hear that their businesses are worth a certain multiple of revenue or earnings. That may sound like a simple way to answer, “What is my restaurant worth?” However, the multiple is only one part of the valuation.
Two restaurants with the same annual revenue can have significantly different values. One may produce consistent earnings after paying reasonable food, labor, occupancy, and management costs. The other may operate with weak margins, depend heavily on its owner, or require substantial equipment investment.
A professional restaurant valuation begins with the financial statements or tax returns. The appraiser evaluates revenue and earnings trends, proposed financial adjustments, and the costs necessary to continue operating the business. Relevant restaurant transactions may then provide evidence of how buyers have valued comparable financial performance.
This guide explains how restaurant valuation multiples work, when SDE, EBITDA, or revenue may be relevant, and how recognized valuation methods are used to determine what a restaurant may be worth in 2026.
What Are Restaurant Valuation Multiples?
A valuation multiple expresses the relationship between the price paid for a business and one of its financial measures.
Common calculations include:
SDE multiple = Relevant transaction price ÷ Seller’s discretionary earnings
EBITDA multiple = Relevant transaction price ÷ EBITDA
Revenue multiple = Relevant transaction price ÷ Revenue
Suppose a restaurant sold for $750,000 and reported normalized SDE of$250,000. Its observed transaction multiple would be:
$750,000 ÷ $250,000 = 3.0 times SDE
That calculation shows the multiple reported for one transaction. It does not establish that every restaurant is worth three times SDE.
Before using the transaction, the appraiser needs to understand:
- Which financial measure was reported
- What financial period was used
- Whether the earnings were adjusted
- What assets and liabilities were included
- Whether inventory or working capital was included
- Whether the transaction was an asset or equity sale
- How comparable the sold restaurant is to the restaurant being valued
The arithmetic is straight forward. Determining whether the transaction provides meaningful valuation evidence requires professional judgment.
Why Isn’t There One Standard Restaurant Valuation Multiple?
Restaurants differ substantially in size, financial performance, operating structure, and risk. Even restaurants in the same segment can generate different earnings from similar revenue.
One restaurant may operate under a favorable lease and have management that runs the business without the owner’s daily involvement. Another may face increasing occupancy costs, depend on the owner to manage every significant decision, or need to replace major kitchen equipment.
These differences influence expected earnings and the risk associated with receiving them. That is why a general restaurant multiple found online cannot determine the value of a specific business.
A multiple should come from relevant market evidence and be paired with the same type of financial measure used to calculate it. The appraiser must also understand what the resulting value includes.
Is SDE or EBITDA Used to Value a Restaurant?
SDE and EBITDA are common earnings measures in restaurant business valuation. The appropriate measure depends on the restaurant’s size, ownership structure, management, and available market evidence.
Seller’s Discretionary Earnings
Seller’s discretionary earnings, or SDE, is often relevant for a smaller restaurant operated by a working owner.
At its most basic level:
SDE = EBITDA + One owner’s compensation
Assume a restaurant reports EBITDA of $200,000 after paying one working owner $125,000. Its basic SDE would be:
$200,000 + $125,000 = $325,000
SDE represents the financial benefit available before paying one owner-operator. If multiple owners work in the restaurant, only one owner’s compensation is added in calculating SDE. Compensation paid to the other working owners remains in salary expense.
This treatment is consistent with SDE transaction multiples, which reflect the benefit available to one owner-operator.
SDE is not the owner’s take-home pay. The restaurant may also need to fund taxes, debt payments, equipment replacement, working capital, and other cash requirements.
EBITDA
EBITDA means earnings before interest, taxes, depreciation, and amortization. It is commonly considered for restaurants with greater financial scale or a management structure that can operate independently of one owner.
EBITDA generally includes reasonable compensation for the management required to run the business. If the owner’s actual compensation is above or below a reasonable amount for the work performed, the expense may require normalization.
Suppose an owner receives $225,000 but the owner’s responsibilities would reasonably cost $150,000 to replace. Subject to appropriate support, the $75,000 difference may be added to normalized EBITDA.
Adding back the owner’s entire compensation would overlook the ongoing cost of replacing the owner’s work.
An SDE multiple must be applied to consistently calculated SDE. A restaurant EBITDA multiple must be applied to EBITDA. The two should not be used interchangeably.
Can Revenue Be Used to Value a Restaurant?
A revenue multiple compares the restaurant’s value with its annual sales. It can provide market context, but revenue does not show whether the restaurant earns a profit.
Consider two restaurants that each generate $2 million in annual revenue. One earns $300,000 after paying its operating expenses. The other earns$75,000. Applying the same revenue multiple to both without considering profitability would overlook a material financial difference.
Revenue multiples are most useful when the underlying transactions and the restaurant’s margins are understood. They generally should not replace an analysis of earnings.
How Are Restaurant Earnings Normalized?
Reported profit may not reflect the restaurant’s expected ongoing performance. Financial normalization evaluates whether particular income or expense items should be adjusted.
Potential adjustments may include:
- Owner compensation above or below a reasonable amount
- Related-party compensation above or below a reasonable amount
- Personal expenses paid by the restaurant
- Related-party rent above or below market
- Non-operating income or expenses
- An unusual gain or loss
- A genuinely nonrecurring expense
- Necessary costs that were deferred or omitted
Each proposed adjustment requires explanation and support. An expense is not automatically removed because it occurred only once.
For example, a restaurant may incur a substantial equipment repair. The specific repair may not recur, but repairs and maintenance are normal costs of operating a restaurant. Adding back the entire expense without considering future maintenance needs could overstate earnings.
Normalization can also reduce earnings. If the restaurant pays below-market rent to a related entity, its normalized occupancy cost may need to increase. If an owner works full time without reasonable compensation, normalized EBITDA may need to recognize the cost of those duties.
The objective is to develop a supportable measure of ongoing earnings, not the highest possible adjusted profit.
Which Historical Periods Are Considered?
A restaurant valuation generally considers multiple financial periods rather than relying automatically on the most profitable year.
The appraiser may review:
- Several completed years
- The latest completed year
- A trailing twelve-month period
- Current year-to-date results
- Material changes occurring after the most recent year
Historical trends help show whether revenue and earnings are growing, declining, or fluctuating. They can also reveal whether one year appears unusual.
A restaurant may have generated strong earnings three years ago but experienced declining revenue and margins since then. A simple historical average could overstate its current earning capacity. Conversely, the latest year may have been affected by a temporary closure or another event that is not expected to continue.
Management’s explanations help the appraiser understand material changes and determine which financial results are most relevant as of the valuation date.
Which Restaurant Expenses Affect Value?
Food, labor, occupancy, and equipment costs determine how much restaurant revenue becomes sustainable earnings.
Food and Beverage Costs
Changes in food and beverage costs directly affect gross profit. Rising sales do not necessarily improve value if ingredient costs increase faster than menu prices.
An appraiser may evaluate historical gross margins and ask management to explain significant changes. The valuation interprets how cost changes appear in the financial results; it does not require an inspection of purchasing practices or individual menu items.
Labor and Management Costs
Labor costs may include kitchen staff, servers, managers, administrative employees, and working owners.
The appraiser evaluates whether the historical expenses reflect the people needed to continue operating the restaurant. If an owner or family member performs necessary work without reasonable compensation, an adjustment may be needed.
Reducing labor expenses in a forecast while assuming the restaurant maintains the same revenue may also require further explanation.
Rent and Occupancy Costs
Lease expense directly affects earnings. If the property is owned by the restaurant owner or a related entity, the recorded rent may not reflect an appropriate market amount.
When the real estate is excluded from the business valuation, the restaurant’s earnings should generally include a reasonable occupancy cost. The real estate and its related debt should be treated separately from the operating business.
Equipment Replacement
Restaurants rely on kitchen equipment, refrigeration, furniture, and point-of-sale systems. EBITDA adds back depreciation, but that does not eliminate the cash required to replace these assets.
Expected equipment spending remains relevant when evaluating the restaurant’s future financial benefits.
How Does the Market Approach Value a Restaurant?
Under the market approach, an appraiser examines sales of other businesses and calculates valuation multiples using their reported prices and financial measures.
Transaction databases may provide:
- Industry classifications and business descriptions
- Revenue
- SDE or EBITDA
- Transaction dates
- Sale prices
- Limited information about deal structure
The amount and quality of information vary. Some transactions may support a meaningful comparison, while others may be excluded or given less weight.
A restaurant’s segment can help identify potentially relevant sales. A quick-service restaurant may not be directly comparable to a full-service fine dining establishment. However, category alone does not establish comparability. Size, revenue, profitability, and the available transaction information also matter.
Transaction databases generally do not provide reliable filters for every operating characteristic. Owner involvement, management depth, lease terms, customer loyalty, and equipment condition may not be available for each sale.
The appraiser considers the subject restaurant’s circumstances when interpreting the market evidence without implying that every operating characteristic was directly matched.
How Does the Income Approach Value a Restaurant?
The income approach estimates the present value of the restaurant’s expected future financial benefits.
If historical performance is reasonably stable, an appraiser may develop a representative ongoing earnings or cash flow measure. When the restaurant is expected to change materially, a forecast over multiple periods may better reflect future performance.
A forecast may need to consider:
- Expected sales
- Food and beverage costs
- Labor and management expenses
- Rent and occupancy costs
- Equipment purchases
- Working capital
- Taxes and other cash requirements
A revenue projection without the associated costs does not provide a complete picture. Opening another location may create growth, but it may also require construction, equipment, staffing, marketing, and working capital.
The income approach must reflect both the expected benefits and the risk of receiving them. Projections based on unsupported assumptions generally require more caution than expectations grounded in established performance.
When Is the Asset Approach Relevant?
The asset approach considers the restaurant’s assets and liabilities. It may provide useful evidence when tangible assets represent a substantial portion of value or when earnings do not support significant operating value.
Restaurant assets may include kitchen equipment, furniture and fixtures,inventory, vehicles, and real estate if owned by the company.
Book value does not necessarily equal current economic value. Equipment may be worth more or less than its recorded amount, and inventory may need evaluation based on what is usable and transferable.
For a profitable operating restaurant, the assets required to generate earnings are generally reflected in an earnings-based value. Adding the same equipment again could double count its value. Excess or non-operating assets may warrant separate consideration.
If the value of specific kitchen equipment is needed, a separate machinery and equipment appraisal may be appropriate. A restaurant business valuation and an equipment appraisal answer different questions.
How Do Restaurant Type and Owner Involvement Affect Value?
A quick-service restaurant, franchise, café, food truck, fine dining restaurant, and multi-location restaurant can have different cost structures. Those differences may appear in labor expense, occupancy costs, gross margins, management needs, and capital investment.
Restaurant type does not create an automatic premium or discount. The appraiser focuses on the company’s actual financial results.
Owner involvement also affects the analysis. The owner may serve as general manager, chef, bookkeeper, purchaser, or primary decision-maker. If the owner leaves, the buyer may need to pay someone to perform those duties.
If EBITDA does not include reasonable compensation for necessary owner functions, normalized earnings may be overstated. A restaurant with management already reflected in its expenses may be less dependent on the owner, making its historical earnings more transferable.
How Does the Lease Affect Restaurant Value?
A restaurant’s location may be important, but the valuation focuses on the financial and contractual effect of its occupancy arrangement.
Relevant questions may include:
- What rent is reflected in the financial statements?
- Will the rent change?
- How much time remains on the lease?
- Are renewal options available?
- Is the lease expected to transfer?
- Does the restaurant pay a related party?
An unfavorable rent increase can reduce expected earnings. A lease with limited remaining time may affect the buyer’s ability to continue operating at the location.
A business valuation is not automatically a legal review of the lease. Owners and buyers should have qualified counsel review transfer, renewal, default, and change-of-control provisions. The appraiser considers the information provided and its financial effect.
How Are Inventory, Equipment, and Working Capital Treated?
The treatment depends on the valuation method and what the comparable transaction prices included.
Operating equipment required to produce the restaurant’s earnings is generally reflected in the operating business’s value. It should not automatically be added again.
Inventory may require separate consideration if it was excluded from the comparable transaction prices. If normal inventory was already included, adding it again would double count it.
Working capital is the operating capital needed to support the business. If a valuation method assumes normal working capital is included, it should not be added separately. An actual sale agreement may establish a working capital target and adjust the final price based on the amount delivered at closing.
Consistent treatment is essential. Assets cannot be included in the earnings-based value and then added again merely because they appear on the balance sheet.
Worked Example: Applying a Restaurant SDE Multiple
Assume an owner-operated restaurant reports:
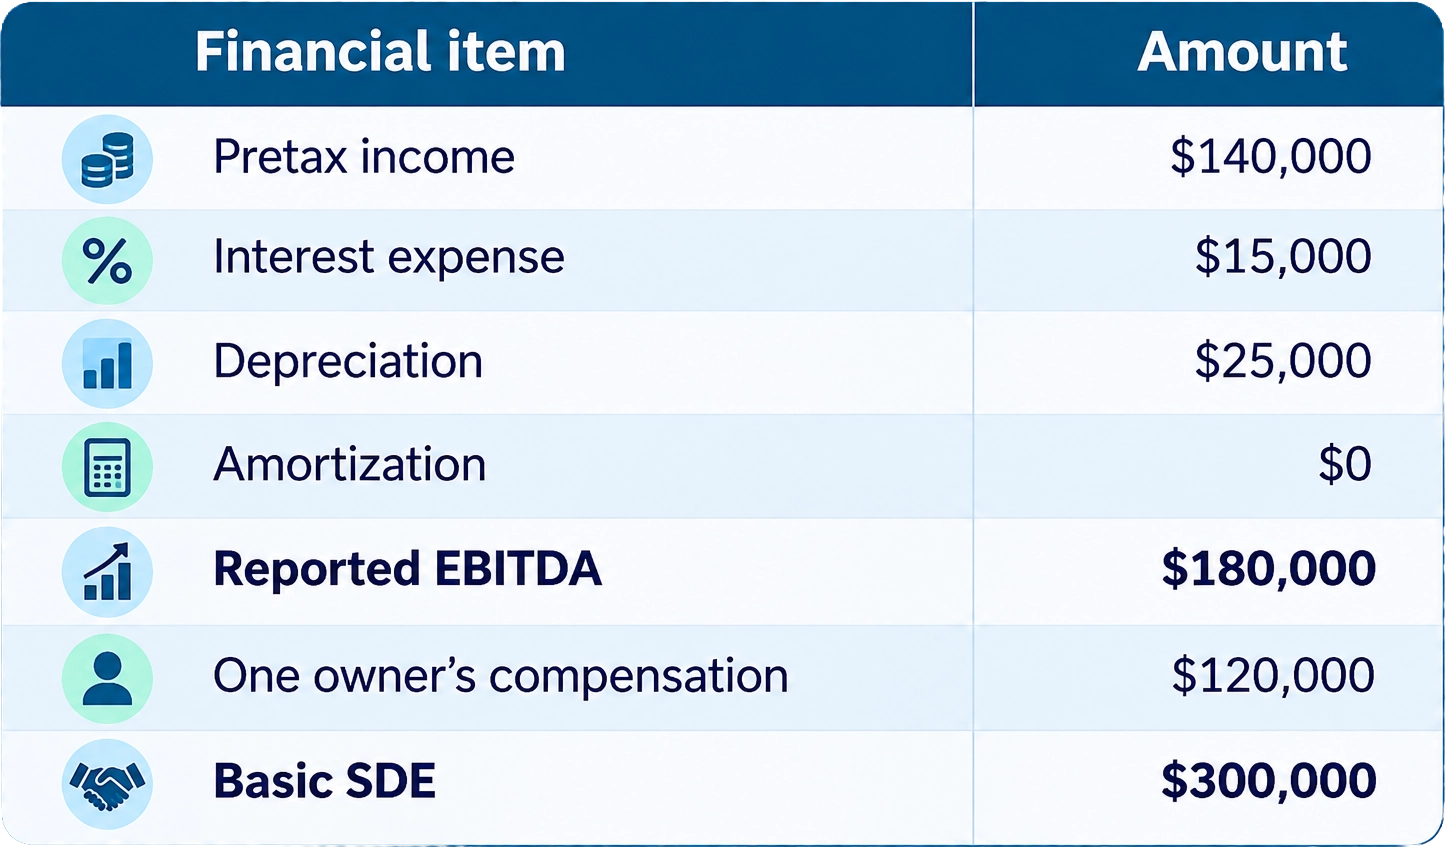
Assume the appraiser also supports:
- A $15,000 add-back for a personal expense
- A $10,000 reduction for bleow-market related-party rent
Normalized SDE would be:
$300,000 + $15,000 − $10,000 = $305,000
The appraiser then reviews relevant restaurant transactions, confirms their financial measures and price definitions, and selects an appropriate SDE multiple based on that evidence.
After applying the multiple, the appraiser determines what the comparable prices included and how debt, excess cash, inventory, and any non-operating assets should be treated.
The example demonstrates the process without suggesting that one multiple applies to every restaurant.
Is Restaurant Value the Same as the Selling Price?
No. A valuation estimates value as of a specified date under defined assumptions. A selling price reflects the transaction negotiated between a particular buyer and seller.
The agreement may determine:
- Whether the transaction is an asset or equity sale
- Which assets and liabilities transfer
- How inventory and working capital are treated
- Whether debt must be paid at closing
- Whether the seller finances part of the price
- Whether any payments depend on future performance
Taxes, broker commissions, legal fees, and debt payoffs can further affect the amount the owner retains.
The value of the operating restaurant, the negotiated purchase price, and the seller’s net proceeds are related but different figures.
Common Restaurant Valuation Mistakes
Applying an Industry Average Without Reviewing the Restaurant
An average multiple cannot account for the company’s earnings, size, financial trends, or transaction assumptions.
Applying an EBITDA Multiple to SDE
SDE and EBITDA represent different levels of earnings. Their multiplesare not interchangeable.
Valuing the Restaurant on Revenue Alone
Revenue does not reflect food, labor, rent, and management costs.
Adding Back Every Owner Expense
Some owner-related expenses may be necessary for operations. Each proposed adjustment requires separate review.
Ignoring Below-Market Expenses
Low rent, unpaid family labor, or inadequate owner compensation can overstate reported earnings.
Adding Equipment Twice
Operating equipment is generally reflected in an earnings-based value and should not automatically be added again.
Confusing Business Value With Net Proceeds
Debt, taxes, transaction expenses, and payment terms affect what the seller ultimately receives.
What Information Is Needed for a Restaurant Valuation?
Helpful information generally includes:
- Historical business tax returns or financial statements
- Recent interim financial results
- Explanations of signifcant revenue or margin changes
- Owner compensation and duties
- Proposed financial adjustments and supporting detail
- Rent and lease information
- Debt and signficant asset information
- Known equipment replacement needs
- Management's expectations for future performance
Additional information may be requested to address a material issue. BizWorth does not collect a complete general ledger as a standard requirement, although relevant account detail may help support a proposed adjustment.
Frequently Asked Questions
What is the best multiple for valuing a restaurant?
There is no multiple that applies to every restaurant. The appraiser selects and interprets market evidence based on the restaurant’s financial measure, size, performance, and available transaction data.
Is a restaurant valued on revenue or profit?
Both may be considered, depending on the valuation method and market evidence. SDE and EBITDA generally provide more information about profitability than revenue alone.
Can I add my salary back when valuing my restaurant?
One owner’s compensation is added to EBITDA when calculating SDE. For normalized EBITDA, reasonable compensation for the owner’s necessary duties generally remains an expense.
Does restaurant equipment increase the value?
Operating equipment needed to generate the restaurant’s earnings is generally included in its operating value. Excess or non-operating equipment may be considered separately.
Does the value include the restaurant’s real estate?
Only if the real estate is included in the company or interest being valued. When the property is excluded, the restaurant’s earnings should generally reflect an appropriate rent expense.
Will a valuation tell me what I can sell my restaurant for?
A valuation provides an estimate under defined assumptions. The final price and net proceeds depend on buyer demand, due diligence, financing, transaction structure, and negotiated terms.
Bringing It All Together
Restaurant valuation multiples provide useful market evidence, but they do not value a restaurant by themselves.
A supportable valuation begins with the restaurant’s financial statements or tax returns. The appraiser evaluates revenue and earnings trends, owner compensation, proposed adjustments, occupancy costs, equipment needs, and other factors affecting sustainable financial performance.
SDE may be appropriate for a smaller owner-operated restaurant. EBITDA may be more relevant when the business includes reasonable management costs. Revenue multiples may provide context when profitability and transaction terms are understood. In every case, the earnings measure and multiple must be consistent.
At BizWorth, we analyze the restaurant’s historical financial performance, discuss material changes with owners or management, evaluate proposed adjustments, and review relevant transaction evidence. That process provides a clearer and more supportable answer to what a restaurant may be worth in 2026
